Financing Your Manufactured Home in New York
How manufactured home loans work, which programs apply, and what you need to get pre-approved.
Most buyers in our communities finance their home with a manufactured-home loan secured by the home itself, since the home sits on a leased site. VA, FHA, and conventional programs are all available through lenders who specialize in manufactured housing, and current residents may add up to $10,000 in down payment assistance through our Loyalty Program.
How manufactured home financing works
There are two common ways to finance a manufactured home, and the difference comes down to what the loan is secured by. A chattel loan (sometimes called a home-only loan) is secured by the home itself, not the land. It is the typical route when your home sits on a leased site in a community, which is how our communities are set up. Chattel loans usually close faster and involve less paperwork, with shorter terms and higher rates than a traditional mortgage.
A mortgage is secured by the home and the land together, so it applies when the buyer owns the land the home is placed on. Mortgages generally offer longer terms and lower rates, but they require the home to be permanently affixed and titled as real property, plus an appraisal and a longer closing process.
Because homes in our communities are placed on leased sites, most of our buyers use a chattel or manufactured-home program. Your lender will confirm which product fits your situation and what your monthly payment looks like before you commit to anything.
VA loans for manufactured homes
VA financing can be used for manufactured homes, subject to lender approval and VA program guidelines. Eligible service members, veterans, and surviving spouses may be able to finance with little or no down payment, and VA loans do not require monthly mortgage insurance.
Not every lender writes VA loans on manufactured housing, so it matters who you apply with. We will point you to lenders who handle manufactured homes and VA files regularly.
Fort Drum families
Indian River Estates in Theresa is about 20 minutes from Fort Drum. We can time delivery and setup around PCS report dates, and many families compare a new home payment plus lot rent directly against their BAH. See our Watertown and Fort Drum area page for commute and community details.
Watertown & Fort Drum area →FHA and conventional options
FHA programs include options built for manufactured housing, including home-only loans for homes on leased sites. FHA programs are known for lower down payment requirements and more flexible credit standards, with mortgage insurance included in the payment.
Conventional manufactured-home programs are also available through lenders who specialize in this housing type. These typically ask for a stronger credit profile and a larger down payment, and in exchange can offer better pricing over the life of the loan.
Rates, terms, and down payment requirements change over time and vary by lender and by borrower. We do not quote rates. Your lender will give you real numbers in writing once you apply.
Using the Loyalty Program as your down payment
If you already live in one of our communities, the Community Loyalty Appreciation Program can supply up to $10,000 toward your down payment. It is tiered by residency length, it is applied at closing rather than paid to you, and it is not a loan you repay.
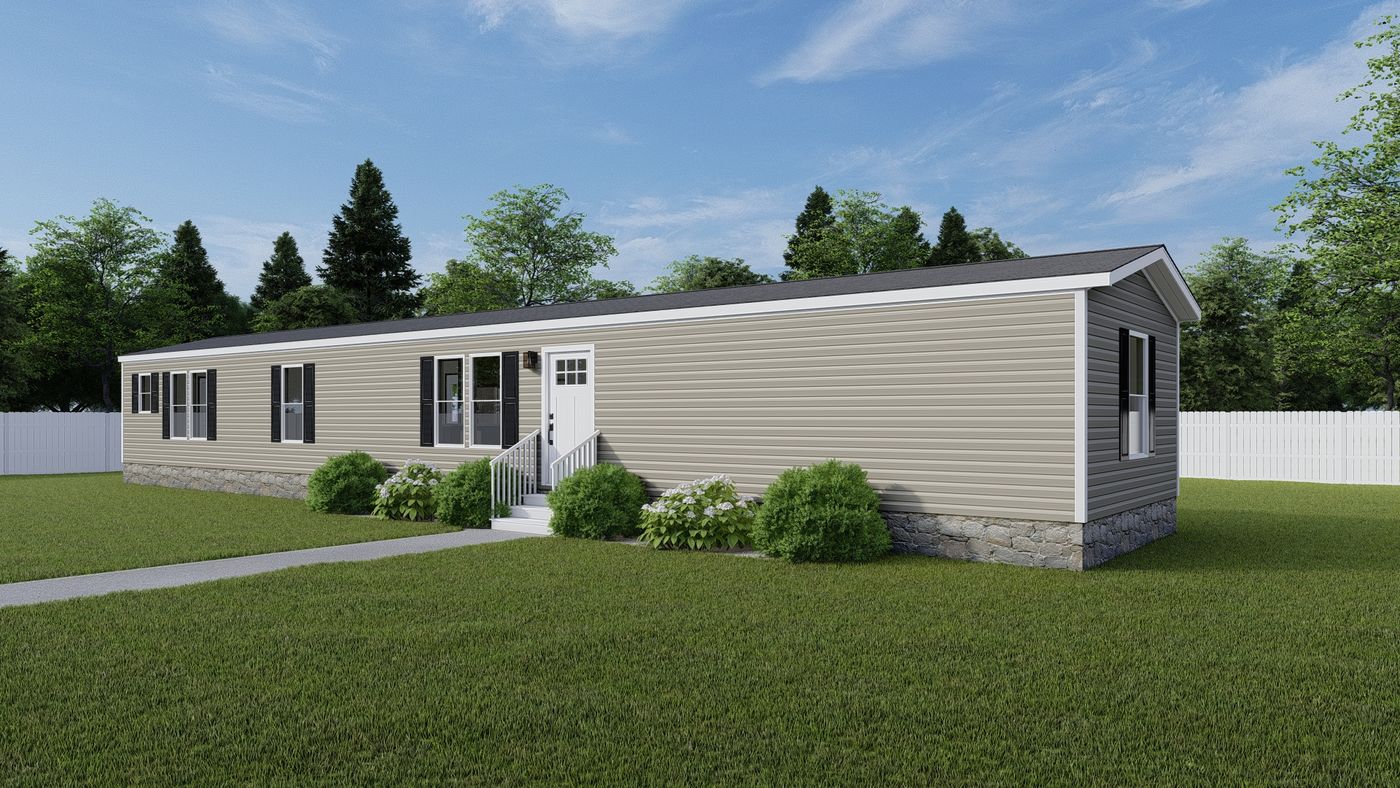
On the Hudson 16x76 at $135,000 installed, $10,000 covers a 7.4 percent down payment, which reduces the amount you finance and can improve the terms your lender is able to offer.
Up to $10,000 in assistance
Current residents may qualify for up to $10,000 toward a new home. Eligibility is based on residency length and account standing, and is confirmed in writing before you reserve.
See the Loyalty Program →What you'll need to apply
Frequently asked questions
Yes. VA financing can be used for manufactured homes, subject to lender approval and VA program guidelines. Eligible buyers may finance with little or no down payment and no monthly mortgage insurance. Not all lenders write VA loans on manufactured housing, so apply with one that does. We can point you in the right direction.
There is no single cutoff. Manufactured-home lenders look at credit history, income, debt load, and down payment together, and different programs have different minimums. Government-backed programs are generally more flexible than conventional ones. The practical step is a free pre-approval, which tells you exactly where you stand.
A chattel loan is secured by the home only, which fits homes on leased community sites like ours. It closes faster with less paperwork, but terms are shorter and rates higher. A mortgage is secured by the home and the land together, requires land ownership, and generally offers longer terms and lower rates.
It depends on the program and your credit profile. Some government-backed options allow very little down, while conventional manufactured-home programs typically ask for more. If you are a current resident, the Community Loyalty Appreciation Program can provide up to $10,000 toward the down payment on a new home.
No. Dolorean Development Corporation is not a lender, mortgage broker, or financial advisor. We sell and place the homes, and we connect buyers with third-party lenders who finance manufactured housing. All loan terms, approvals, rates, and disclosures come directly from the lender you choose.
Important disclaimer
Dolorean Development Corporation is not a lender, mortgage broker, or financial advisor, and does not originate loans or issue credit decisions. We connect buyers with independent third-party lenders who finance manufactured homes. All loan programs, interest rates, terms, fees, approvals, and required disclosures come directly from the lender you choose and are subject to their underwriting and to program availability. Nothing on this page is an offer of credit or a guarantee of financing.
Talk to us about financing your new home
Ask about availability, delivery timing, and financing. We will walk you through pricing and next steps.